Greed and Capitalism

What kind of society isn't structured on greed? The problem of social organization is how to set up an arrangement under which greed will do the least harm; capitalism is that kind of a system.
- Milton Friedman

Friday, August 31, 2018

Rosneft May Challenge Crystallex Claim To Citgo Shares


Will this be an American court going up against one of Putin's Oligarcs?


U.S. Judge Allows Crystallex Claim To Citgo Shares

Venezuela creditors eye oil assets over unpaid debt Venezuela’s sliding oil exports a boon for prices Venezuela national oil company sued in New York fast

FT Petroleos de Venezuela SA US judge allows Crystallex to seize Venezuela’s Citgo Decision over US-based oil refiner is another financial blow to cash-strapped nation 

Venezuela’s efforts to stay afloat financially have suffered another blow after a judge in the US gave a Canadian mining company permission to seize the shares of the Venezuelan holding company that owns Citgo, a US oil refiner. 

The judge on Thursday ruled that Canada’s Crystallex has the right to claim the shares of PDV Holding Inc to compensate it for around $1.4bn it is owed by the Venezuelan state. 

The case dates back to 2011 when Venezuela nationalised Las Cristinas, a gold reserve owned by Crystallex. The Canadian company took Venezuela to the World Bank’s international arbitration tribunal ICSID and won, but Venezuela refused to pay up. 

Crystallex therefore went after Citgo as compensation, arguing that PDV Holding Inc, which is owned by Venezuela’s state-owned oil company PDVSA, is essentially an “alter ego” of the Venezuelan state. 

The case is one of many arbitration cases involving Venezuela and foreign companies. 

Earlier this year US oil company ConocoPhillips tried to seize PDVSA assets in the Caribbean, including products stored at its Isla refinery on the island of Curaçao. 

Citgo is the jewel in the crown of PDVSA’s foreign holdings. The Houston-based company not only operates gas stations but has three refineries in the US with a capacity to refine 750,000 barrels of crude a day. 

It also produces lubricants which are vital for Venezuela’s refining of its heavy crude. 

Ángel Alvarado, a Venezuelan opposition member of Congress and an economist, said Thursday’s decision was an even bigger blow to PDVSA that the ConocoPhillips move “because it will seriously affect the import of diluents from the US, one of the raw materials for the extraction of heavy and extra-heavy crude.” 

In his brief ruling, Judge Leonard Stark of the Delaware District court did not give his reasoning. His full decision is under seal. 

“Crystallex and PDVSA shall meet and confer and, no later than August 16, 2018, submit a joint status report providing their position(s) as to how this case should now proceed,” he said.


 Link: https://www.ft.com/content/70189b76-9c43-11e8-9702-5946bae86e6d


Rosneft May Challenge Crystallex Claim To Citgo Shares

oil storage
Rosneft has asked a U.S. federal court to establish “a robust appraisal and sale process” of Citgo shares following Canadian miner Crystallex’ win at court against the parent company of Citgo, PDVSA, Argus Media reports citing documents submitted by Rosneft to court.

"Such a course of action is particularly appropriate under the circumstances given the multitude of parties and interests potentially affected by a sale of PdVH," the documents said.

Crystallex was ruled the winner in a long-running case against Venezuela, which it has sued over the forced nationalization of its assets by the Hugo Chavez government. A U.S. federal judge last week awarded the miner the right to approach Venezuela’s U.S. oil unit, Citgo, to seek its compensation of US$1.4 billion.

Yet the Russian state company has priority rights over 49.9 percent in Citgo. PDVSA used the stake as collateral for a US$1.5-billion loan provided by Rosneft in 2016. 

The move at the time sparked a lot of negative comments in the United States, with some legislators worried that Rosneft could at some point take control over the U.S. company. The rest of the Citgo stock has been pledged as collateral to a PDVSA bond issue that matures in two years, Argus Media notes.

Now Crystallex wants to take control over the refiner, which operates a refinery network with a daily capacity of 750,000 bpd, and then sell the stock on to another investor or investors to get its US$1.4 billion. 

The sum was awarded to the Canadian miner as compensation for the forced nationalization of its operations in Venezuela by the Hugo Chavez government.

At the time, the Associated Press noted that the ruling by Chief Judge Leonard P. Stark is unique: government assets such as Citgo’s parent, PDVSA, are as a rule protected from lawsuits targeting a state. 

Yet in Stark’s ruling, the judge said that Venezuela had blurred the lines between the government and the state oil firm, with a military official at the helm of PDVSA.

By Irina Slav for Oilprice.com  


Link: https://oilprice.com/Latest-Energy-News/World-News/Rosneft-May-Challenge-Crystallex-Claim-To-Citgo-Shares.html


Monday, July 16, 2018

F.A. Hayek


JUST IN: Goldman to name David Solomon as next CEO early this week, New York Times reports


George Eastman: The Greatest Tech Entrepreneur In U.S. History : The technologies of today are built upon those of the past, and the superstars of our era would be nothing without the great leaders of... -


'The Road To Serfdom': 7 Things You Might Not Know About Hayek's Classic Book : Most college students—and many other people, for that matter—at some point encounter F.A. Hayek's popular book The Road to Ser... 


Thursday, July 12, 2018

Sustainable Finance

 
Sustainable finance must become the new normal. Six sovereign wealth funds which collectively represent more than US$ 3 trillion in assets have committed to only invest in companies that factor climate risks into their strategies. 


Wednesday, June 20, 2018

The Meaninglessness of the Stock Market Index in a Digital World


General Electric, which has been a component of the Dow Jones Industrial Average since Teddy Roosevelt was president in 1907, will be pulled out of the basket of 30 stocks next week. It’ll be replaced by ... Walgreens.

Why’d GE get bounced? It probably has something to do with the company’s fortunes. While it still generates a tremendous amount of revenue—$120 billion in 2017—its margins have fallen, and it swung into the red in each of the past two quarters. As a result, GE’s shares have fallen roughly 60 percent, from highs close to $32 per share at the end of 2016 down to today’s close at $12.88. Its shares performed the worst of any in the Dow last year.


The index is supposed to represent the country’s 30 biggest, best companies out of the more than 3,500 publicly listed corporations. The committee that oversees the index did not give a technical reason for the demotion. Instead, David Blitzer, the chairman of the index committee at S&P Dow Jones Indices, gave a more nuanced statement, referencing GE’s continuous inclusion since 1907.
Since then the U.S. economy has changed: Consumer, finance, health care, and technology companies are more prominent today and the relative importance of industrial companies is less. Walgreens is a national retail drugstore chain offering prescription and nonprescription drugs, related health services, and general goods. With its addition, the DJIA will be more representative of the consumer and health-care sectors of the U.S. economy. Today’s change to the DJIA will make the index a better measure of the economy and the stock market.
If you’re thinking, “That sounds kind of arbitrary,” you’re not wrong. How does adding up the share prices of 30 handpicked stocks and then dividing by a mutable “divisor” to normalize the index into a single number measure “the economy and the stock market”?


Well, the DJIA has tracked the S&P 500 remarkably well through time. As the longest-running important stock market index, the DJIA allows for historical comparisons that stretch back over 100 years. That’s useful. There is a nostalgic comfort in thinking that the same single number, composed of a potpourri of well-known companies nominally headquartered in this country, represent the American role in the massively complex, globalized economy.

However: The index probably can’t include the really high-priced stocks like Google and Amazon.

Back in 2012, Adam Davidson argued that the index isn’t even a good measure of the companies that it contains, because the price of an individual share of a company is not the best measure of its value to investors. If all you do is add up the share prices and then divide, you get strange results. Given the same market value, a company with fewer shares outstanding will have a higher share price—and therefore a bigger impact on the index—than a company with more shares outstanding. And if you have a huge market cap and fewer shares outstanding, then you get share prices like Amazon’s, which is trading over $1,750 today. Walgreens shares are trading below $70. Would it make sense to have Amazon’s impact on the index hit at more than 25 times Walgreens’s? What’s the point of a bundle of stocks at that point?

Nonetheless, this is the way that the DJIA has done things before, so that’s the way it continues.

Besides, share prices are, themselves, becoming detached from the traditional measures of value for companies. Digital companies, in particular, are valued differently from industrial giants like GE, three business-school professors argued in the Harvard Business Review.

“Accounting earnings are practically irrelevant for digital companies,” the professors wrote. The things that investors value about Amazon and Facebook—the chance they will get huge and dominate markets with incredibly high margins—are not reflected in earnings reports.

“In another study, we show that earnings explains only 2.4 percent of variation in stock returns for a 21st-century company—which means that almost 98 percent of the variation in companies’ annual stock returns are not explained by their annual earnings,” they continue.

For example, for fiscal year 2017, Costco had earnings per share of $6.08. Amazon had earnings per share of $6.15. Costco’s market value is $91 billion; Amazon’s is $844 billion.

Amazon certainly seems like a more important company. But is it 9.3 times more important? The mathematical precision of the stock market, no matter how it’s indexed, just does not map well onto the messy realities of the economy.

If what we want is a snapshot of the economy, like the real one that you and I live and work in, then the Dow Jones Industrial Average, and the rest of the stock market, are probably not the best indicators for the average American.


“The stock market might actually be our worst option. Rather than being a useful indicator, it’s an anxiety-amplification device. It reflects investors’ own reactions, and often hysterical overreactions, as they progress through the turmoil,” Davidson wrote. “It’s also not without intrinsic randomness. The Dow average, drawn out to two decimal places, may seem like some perfectly scientific number, but it’s far from it.”

It was helpful in the past to be able to answer the question, “Were the markets up or down?”—by which most people meant, “Was it a good day for the economy?” It was even more helpful to have that answer be a number that could tracked over time. But the DJIA is a vestige of a time when people didn’t have nearly as much access to different kinds of information about companies or the economy more broadly.

So, GE’s out of the Dow Industrial Average and Walgreens is in. Each of them employs an order of magnitude more people than Facebook, which has triple the market capitalization of GE and Walgreens combined. How do these numbers relate to each other or the lived reality of people with hourly wages or salaries?

The world still spins, and the stock market goes up and down. 


 Source: https://www.theatlantic.com/author/alexis-madrigal/


Saturday, May 26, 2018

Shared housing startups are taking off


 https://techcrunch.com/2018/05/19/shared-housing-startups-are-taking-off/


Shared housing startups are taking off


 Joanna Glasner is a reporter for Crunchbase.

 
What does it take to be a startup that raises huge sums quickly?

Not a minimalist? Startups will gladly store, manage and deliver your items


When young adults leave the parental nest, they often follow a predictable pattern. First, move in with roommates. Then graduate to a single or couple’s pad. After that comes the big purchase of a single-family home. A lawnmower might be next.

Looking at the new home construction industry, one would have good reason to presume those norms were holding steady. About two-thirds of new homes being built in the U.S. this year are single-family dwellings, complete with tidy yards and plentiful parking.


In startup-land, however, the presumptions about where housing demand is going looks a bit different. Home sharing is on the rise, along with more temporary lease options, high-touch service and smaller spaces in sought-after urban locations.

Seeking roommates and venture capital

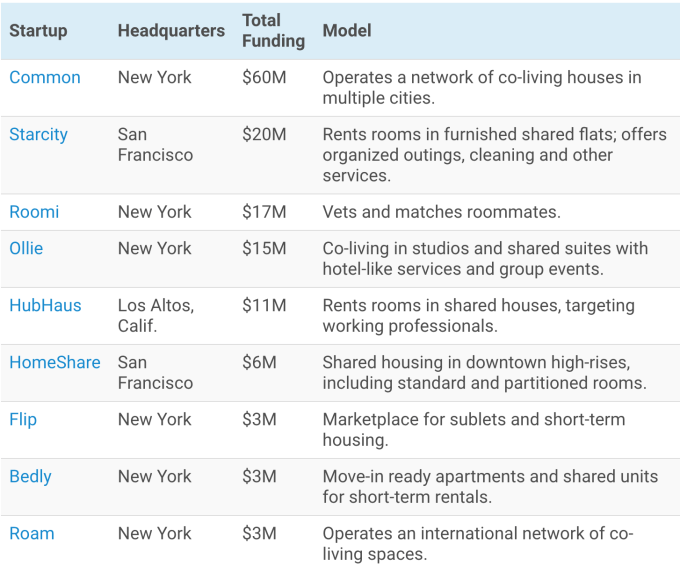
A Crunchbase  News analysis of residential-focused real estate startups uncovered a raft of companies with a shared and temporary housing focus that have raised funding in the past year or so.

This isn’t a U.S.-specific phenomenon. Funded shared and short-term housing startups are cropping up across the globe, from China to Europe to Southeast Asia. For this article, however, we’ll focus on U.S. startups. In the chart below, we feature several that have raised recent rounds.


Notice any commonalities? Yes, the startups listed are all based in either New York or the San Francisco Bay Area, two metropolises associated with scarce, pricey housing. But while these two metro areas offer the bulk of startups’ living spaces, they’re also operating in other cities, including Los Angeles, Seattle and Pittsburgh.

From white picket fences to high-rise partitions

The early developers of the U.S. suburban planned communities of the 1950s and 60s weren’t just selling houses. They were selling a vision of the American Dream, complete with quarter-acre lawns, dishwashers and spacious garages.

By the same token, today’s shared housing startups are selling another vision. It’s not just about renting a room; it’s also about being part of a community, making friends and exploring a new city.

One of the slogans for HubHaus is “rent one of our rooms and find your tribe.” Founded less than three years ago, the company now manages about 80 houses in Los Angeles and the San Francisco Bay Area, matching up roommates and planning group events.

Starcity pitches itself as an antidote to loneliness. “Social isolation is a growing epidemic—we solve this problem by bringing people together to create meaningful connections,” the company homepage states.

The San Francisco company also positions its model as a partial solution to housing shortages as it promotes high-density living. It claims to increase living capacity by three times the normal apartment building.

Costs and benefits

Shared housing startups are generally operating in the most expensive U.S. housing markets, so it’s difficult to categorize their offerings as cheap. That said, the cost is typically lower than a private apartment.

Mostly, the aim seems to be providing something affordable for working professionals willing to accept a smaller private living space in exchange for a choice location, easy move-in and a ready-made social network.

At Starcity, residents pay $2,000 to $2,300 a month, all expenses included, depending on length of stay. At HomeShare, which converts two-bedroom luxury flats to three-bedrooms with partitions, monthly rents start at about $1,000 and go up for larger spaces.

Shared and temporary housing startups also purport to offer some savings through flexible-term leases, typically with minimum stays of one to three months. Plus, they’re typically furnished, with no need to set up Wi-Fi or pay power bills.

Looking ahead

While it’s too soon to pick winners in the latest crop of shared and temporary housing startups, it’s not far-fetched to envision the broad market as one that could eventually attract much larger investment and valuations. After all, Airbnb has ascended to a $30 billion private market value for its marketplace of vacation and short-term rentals. And housing shortages in major cities indicate there’s plenty of demand for non-Airbnb options.

While we’re focusing here on residential-focused startups, it’s also worth noting that the trend toward temporary, flexible, high-service models has already gained a lot of traction for commercial spaces. Highly funded startups in this niche include Industrious, a provider of flexible-term, high-end office spaces, Knotel, a provider of customized workplaces, and Breather, which provides meeting and work rooms on demand. Collectively, those three companies have raised about $300 million to date.

At first glance, it may seem shared housing startups are scaling up at an off time. The millennial generation (born roughly 1980 to 1994) can no longer be stereotyped as a massive band of young folks new to “adulting.” The average member of the generation is 28, and older millennials are mid-to-late thirties. Many even own lawnmowers.

No worries. Gen Z, the group born after 1995, is another huge generation. So even if millennials age out of shared housing, demographic forecasts indicate there will plenty of twenty-somethings to rent those partitioned-off rooms.


Image Credits: Bryce Durbin /


Source: https://techcrunch.com/2018/05/19/shared-housing-startups-are-taking-off/


Tags
Collaborative Consumption
Column
TC
affordable housing
Airbnb
business

Shared housing startups are taking off


Joanna Glasner Contributor More posts by this contributor These schools graduate the most funded startup CEOs The formula behind San Francisco’s startup success When young adults leave the parental...


Friday, May 25, 2018

The London Whale Guy


 Banks

The London Whale Guy Would Like To Have A Few Hundred Thousand Words With Jamie Dimon


Bruno Iksil, the trader who rose to infamy as JPMorgan’s London Whale in 2012, has finally decided to tell his whole story. It’s not a simple tale. Nor is it a brief one. In fact – at more than 150,000 words spread across a half-dozen pdf documents uploaded to a website called the London Whale Marionette (first reported by Financial News London) – it’s longer than most novels. But if one overriding theme can be gleaned from the rambling and minimally organized welter of information Iksil has regurgitated into the web, it’s this: Jamie Dimon is a jerk.
But it takes a heroic expenditure of time and concentration to get to that conclusion. Single-spaced paragraphs that go on for pages at a time spell out a stream-of-consciousness narrative that is only loosely chronological. As Iksil writes early on:
Many readers will find the text dense and at times difficult to grasp. I apologize for that. What makes it difficult is not the underlying trading and banking universe that is pictured in the background. The real challenge is that this case is just a series of smokes and mirrors.
He later apologizes that “my English is sometimes quite clumsy.” This is true, but sometimes his diction sings. E.g., this sentence: “Who could gobble such a gross bluff?” Really, who?
In his version of the London Whale story, Iksil was a patsy, or, in a characteristic gallicism, a “marionette.” He was simply a tool for higher-ups in JPMorgan’s Chief Investment Office, swallowing his own misgivings to wind and unwind massive and risky trades whose ostensible purpose was to hedge the bank’s overall risk profile but in actuality functioned as soon-to-be-verboten proprietary trades intended solely to make money. When the music stopped, he was discarded.
This much can be reasonably inferred from previous overviews of the London Whale imbroglio, including the 2013 Senate investigation and, to a lesser degree, JPMorgan’s own, somewhat exculpatory self-examination. But the full story hasn’t been understood yet, Iksil writes, thanks to a credulous press and lazy regulators:
Only a small fraction of the existing evidence on that matter is available today for the public eye through the US Senate report exhibits…. And this small fraction itself is sort of buried in the middle of 2500 pages with no thread to guide the reader.

Apparently seeking to outdo the incomprehensibility of the Senate’s muddled report, Iksil’s saga weaves together emails, court documents, press clips and personal reflections into what is either a post-modern literary masterpiece or a length demonstration of the importance of having a good editor.

Anyway, the short version is this:

The “London Whale” is a genuine scandal. It appears to be a genuine manipulation of the markets, a genuine manipulation of the bank accounts, and a genuine manipulation of the media. It may be even worse than that if the final outcome on the “London Whale” is the one that prevails today in 2017.
Contrary to public perception, the ill-fated maneuver that caused such embarrassment for Dimon et al didn’t leave JPMorgan $6.2 billion in the red, Iksil writes, but some $25 billion in the black. That’s because the synthetic credit derivative shorts that the CIO had piled into so heavily were balanced out by long positions in the investment bank. The whole thing – minus the whole losing-billions-on-a-single-position-and-paying-huge-fines part – had been planned all the way back in 2010, Iksil writes. Taken as a whole, the Whale days were actually a good time for JPMorgan:
The year 2012, far from being a catastrophe, was quite a unique successful vintage for JpMorgan since 1999 and would still look like the best one year on the record in 2017 when the tangible capital generation is considered. One would then better understand why, back in 2012, the bank simply did NOT plan to unwind the position of the ‘CIO hedge‘ in the markets…It was already positioned to make a profit on the long planned “CIO tranche book” transfer to the IB and to hedge funds. This sheds quite a different light upon the events that are described through the media coverage part before. This implies for example that the positions offsetting those of CIO were already present in the firm, valued by the IB (the Investment Bank of JpMorgan), and this suggests that the loss at CIO was not such a worry as far as the bank earnings were concerned throughout the period covering Q1 and Q2 2012. One may then rightly conclude that the losses at CIO were balanced everyday by quite equivalent known gains somewhere else inside JpMorgan. Hence nothing had been left to chance way before the rumor and the articles got to press in April 2012.
This is just the 30,000-foot view. Iksil goes into lugubrious detail about his own side of the story – the warnings he sent upper management, the browbeating he received for those warnings, his sole and fleeting interaction with Jamie (“ Iksil will reply that he is dealing day to day with the ‘nuclear wastes’ of the markets in credit”), his being told that “we manage the optics for regulators here” at the CIO, his acute case of “Burn Out” that took him out of commission during the worst of the fiasco, his unsatisfying interactions with the regulatory state, etc – but we’ll leave it to others to comb through for anything truly revelatory.
The real takeaway, I think, is this. Let’s assume that Iksil is right, that JPMorgan promoted him into a fake position so that they could later lay the blame for the CDS trading losses at his feet. The most important criterion in selecting a good patsy isn’t just whether they’ll play along at first, but whether you can count on them not to (a) blow a whistle, nor (b) prove to be a real liability when everything shakes out. That relies on believability and media savvy, among other things. So go ahead and visit www.londonwhalemarionet.monsite-orange.fr and decide for yourself whether Iksil fits the bill. 

Saturday, May 12, 2018

Bill Benter at the International Congress of Chinese Mathematicians 2004


Bill Benter created software that analysed hundreds of racing stats and
facts.

His software was so successful he made hundreds of millions of
pounds playing races at Hong Kong. 

In this presentation to the ICCM in 2004 he discusses his software and
probabilities used for horse racing in basic terms.